

MoneyLion: Banking & Cash Back

- 41.92K Reviews
- 4.5
- Downloads
- 5,000,000+
Our take on MoneyLion: Banking & Cash Back from Appgk
I approached MoneyLion as a decision rather than a simple download: is it useful to have cash-back opportunities, access to fast cash advance options, personal loan offers, and banking tools gathered in one finance app? My answer is yes for some situations, but not automatically for everyone. The convenience is real, yet the app asks you to compare terms carefully instead of treating every available offer as a bargain.
Developed by MoneyLion Inc., this free finance app is aimed at people who want several money-related services in one place. It is available for everyone by age rating, and its broad appeal is reflected in an average rating of 4.5 from around 218 thousand ratings, with more than 5 million installs. Those figures suggest that it has become a familiar option, but popularity alone should not decide whether it belongs on your phone.
How I Decided Whether MoneyLion Is Worth Using
I would judge this app using four practical questions. First, does it solve a real money problem I have today? Second, can I understand the conditions attached to each feature before using it? Third, is the convenience of one app worth changing the way I manage banking and borrowing? Finally, will I actually use the cash-back and account tools, or will they simply add another place to check?
That last question matters more than it sounds. A finance app can look impressive because it covers many areas, but a long feature list is not the same as a good personal fit. Someone who only wants a basic bank account may prefer a simpler service. Someone who occasionally needs a short-term cushion, wants to browse personal loan offers, and likes managing related money tasks together may see much more value here.
Best Parts of MoneyLion: Banking & Cash Back
Things to Keep in Mind About MoneyLion: Banking & Cash Back
My first practical step would be to install it and explore the available sections before connecting everything. I would read each offer screen, check what action is being requested, and separate everyday banking from borrowing decisions. This creates a useful boundary: I can use the app for organization without feeling pressured to accept every financial product it presents.
One app, several different decisions
The banking area, cash-back opportunities, cash advance access, and personal loan offers should not be treated as one single product. They answer different needs. Banking is about routine money management. Cash back is about getting value from eligible spending or offers. A cash advance is about timing and short-term liquidity. Loan offers involve a much larger commitment and deserve the most careful comparison.
News and Features Related to MoneyLion: Banking & Cash Back

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
I found this separation helpful because it prevents a common mistake: assuming that because a service is displayed conveniently inside a trusted app, it must be the best option. The app can make discovery easier, but I still need to compare repayment details, eligibility, timing, and any applicable costs with alternatives outside it.
A realistic everyday example
Imagine that my paycheck arrives later than expected and an essential bill is due first. I might open MoneyLion to review whether a cash advance option is available, while also checking my account activity and any pending transactions. In that situation, speed and convenience could be more important than searching across several services.
Don't want to read the full review?
However, I would not use the same rushed approach for a personal loan. If I needed money for a large repair or a planned purchase, I would use the app to review available offers, then compare them with my bank or other lenders before making a decision. The important insight is that the app is most useful as a starting point and management hub; it should not replace careful borrowing judgment.
What the interface is really good at
The strongest idea behind MoneyLion is consolidation. Instead of moving between a banking app, a cash-back service, and a separate place to investigate borrowing, I can begin in one environment. That reduces the mental effort of remembering where to look, especially when I am checking finances on a phone.
Screenshots
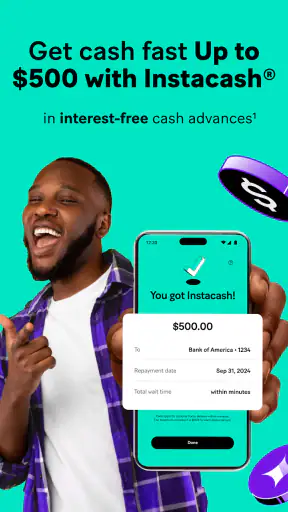
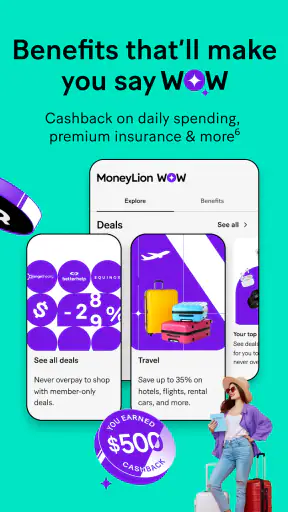
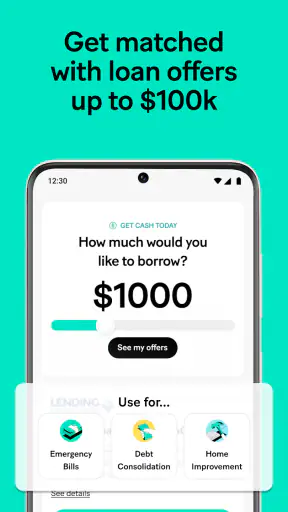
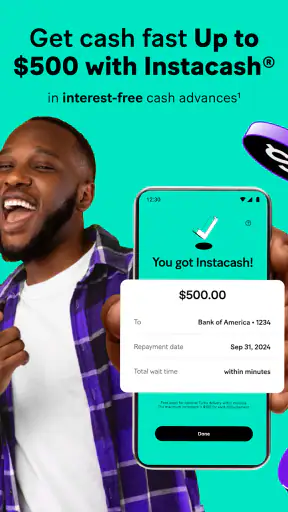
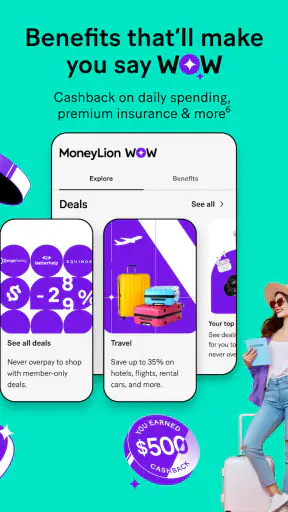
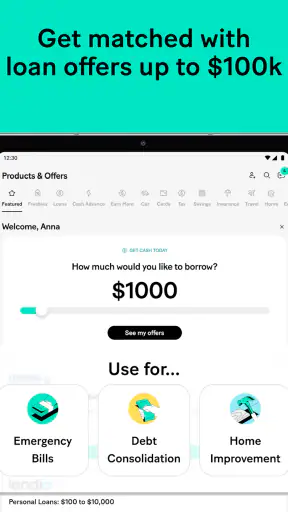
I also like the possibility of using the app in stages. A cautious user can begin by browsing the banking and cash-back areas, learn how the layout works, and only investigate advances or loans when a genuine need appears. This is a better workflow than signing up for every available option immediately.
The app was released on May 19, 2016, and its current version is 7.158.0. For me, those details matter less as selling points than as reminders to keep the app updated and to review the screens as they appear now, rather than relying on an old impression of how a finance service used to work. Money products can change in presentation and availability, so the current in-app terms should always take priority.
Cash back is useful when I make it part of a routine
Cash back sounds effortless, but it only helps if I remember to check the available opportunities before spending. My preferred approach would be to look through the relevant section once or twice a week, identify offers that match purchases I already planned, and ignore anything that encourages unnecessary spending.
That workflow is more valuable than chasing every promotion. If an offer changes what I buy, the reward may not represent a real saving. If it fits an expense already in my budget, the feature becomes a small but sensible way to improve the value of ordinary spending. This is one of the less obvious trade-offs: the app can help me find savings, but it cannot turn an unnecessary purchase into a financially smart one.
Fast cash can solve timing problems, not income problems
The cash advance option is potentially useful when the issue is a short gap between expenses and incoming money. I would think of it as a timing tool, not as extra income. Before using it, I would confirm the amount, repayment expectations, availability, and any cost shown in the app. I would also ask whether the next paycheck can comfortably cover both the advance and my normal bills.
If the answer is no, the advance is probably postponing the problem. In that case, a conversation with the bill provider, a revised budget, or a longer-term plan may be safer. MoneyLion makes access convenient, but convenience can make a serious decision feel smaller than it is. I would deliberately slow down at the confirmation stage.
Personal loan offers need a wider comparison
Browsing personal loan offers can be convenient, particularly if I want to see possible options without visiting several websites or branches. Still, I would compare the full repayment picture rather than focusing on the amount offered or the apparent speed of approval. The monthly payment, total repayment, term, and conditions all matter.
This is also where a traditional bank or a dedicated lending comparison service may fit better. A bank relationship could be more useful for someone who wants all borrowing decisions handled through an existing institution. A dedicated comparison route may suit a person who wants to focus only on loan terms rather than seeing loans alongside banking and cash-back tools.
Where MoneyLion has the clearest advantage
MoneyLion is strongest when convenience is the main decision criterion. If I want one mobile destination for routine banking, cash-back discovery, short-term cash access, and personal loan research, its combined approach is more practical than maintaining several unrelated apps.
It is also a good fit for people who prefer self-service. I can investigate options on my own schedule rather than beginning with a branch visit or a phone call. That does not guarantee the best outcome, but it can make financial housekeeping less intimidating for someone who is comfortable reading screens and comparing choices.
The broad audience is another advantage. The app is free to download and carries an Everyone content rating, so it is positioned as an accessible general finance tool rather than a niche product for a narrow group. Even so, accessibility should not be confused with suitability for every financial situation.
Where the alternatives may fit better
I would look elsewhere if my priority were simplicity above all else. A conventional banking app may be easier for someone who only wants to view balances, move money, and handle routine payments without browsing advances, cash-back opportunities, or loan offers.
I would also consider separate services if I already have a cash-back system that I understand and use consistently. Switching just to place everything under one roof may not be worth the learning curve. The same applies to borrowing: if my bank already provides clear loan support and I value an established relationship, adding another financial platform may create more administration than benefit.
People who tend to accept preselected offers quickly should be especially cautious. MoneyLion presents multiple financial paths in one place, which is convenient, but that convenience can encourage impulsive choices. If I know I am likely to borrow before checking the full conditions, I would prefer a slower process with fewer prompts and more deliberate comparison.
The real cost of switching
Moving to a new finance app is not only about downloading it. I need to learn the layout, decide which services I actually want, connect relevant accounts if necessary, and create a habit of checking the right sections. I would not move all my financial activity on day one. I would first explore the app, confirm that the banking workflow feels clear, and then introduce one function at a time.
A sensible transition would be to use the app as a secondary dashboard before making it my primary destination. I could review cash-back opportunities and loan information without immediately changing where every transaction happens. This reduces the risk of abandoning a familiar setup before I know whether the new one genuinely saves time.
I would also keep records of any advance or loan decision outside the app. Writing down the amount, expected repayment, and reason for borrowing gives me a clearer view than relying only on notifications. This small habit is particularly useful when several financial features share the same interface and I want to avoid confusing a cash-back reward with available cash.
Questions I would answer before signing up
A reader will reasonably want to know whether the app is free. The download price is free, but that does not mean every financial service inside it has identical terms. I would inspect the specific screen for any advance, loan, or other optional service and read the conditions before proceeding.
Another important question is whether it is suitable for everyday banking. It can be, especially for someone who values a combined mobile experience, but I would test the basic banking workflow first. If I mainly need a quiet, uncomplicated account, the wider range of features may feel unnecessary rather than helpful.
People also ask whether cash advances are a good emergency solution. I would say they can help with a short timing mismatch when repayment is already realistic, but they are not a substitute for stable income or a sustainable budget. The correct decision depends on the next few weeks, not only on the immediate relief.
For loan shoppers, the key question is whether an offer found in the app is automatically better than one elsewhere. It is not. I would use the app to discover and organize possibilities, then compare the complete terms with my bank and other credible alternatives before accepting anything.
Finally, I would ask whether the app suits someone who dislikes financial notifications or frequent offers. If that describes me, a single-purpose banking app may be less distracting. MoneyLion makes sense when I want its range and am willing to manage that range actively.
My recommendation for different types of users
I recommend giving MoneyLion a serious look if you want a free finance app that brings banking, cash-back discovery, fast cash advance access, and personal loan offers into one mobile experience. It is particularly appealing when you value convenience, prefer self-service, and can separate browsing from accepting.
I would recommend it less strongly to someone who wants only basic banking, already has excellent tools for cash back, or prefers to discuss borrowing with a bank adviser. In those cases, a narrower alternative may be easier to understand and less likely to place unrelated financial choices side by side.
My best practical advice is to start slowly: explore the banking and cash-back areas, use cash advances only for manageable timing gaps, and treat personal loan offers as comparisons rather than recommendations. That approach lets the app’s convenience work for me without allowing convenience to make the decision for me.
Overall, MoneyLion is a capable choice for people who want a broad financial toolkit in one place. I like its potential to reduce app-hopping and make money tasks easier to find, but I would keep a careful eye on terms and borrowing habits. With that discipline, the app is most valuable as a flexible financial hub, not as a shortcut around financial judgment.
MoneyLion: Banking & Cash Back FAQ
What is MoneyLion: Banking & Cash Back?
MoneyLion is a personal finance app that combines several money-management tools in one place. Depending on your eligibility and location, it may offer spending and banking features, cash-back rewards, credit monitoring, budgeting tools, financial education, and access to products such as credit-building or cash-advance services. Available features, terms, and pricing can vary, so review each product carefully before signing up.
Is MoneyLion a real bank, and is my money protected?
MoneyLion is a financial technology company rather than a traditional bank. Some banking services may be provided through partner banks, and the applicable protections depend on the specific account and provider. Before depositing money, read the account agreement to confirm eligibility, fees, limits, and whether funds qualify for FDIC insurance or other protections. Do not assume every feature has identical coverage.
Does MoneyLion charge fees or require a subscription?
MoneyLion offers both free and paid features, and costs depend on the products you choose. Certain services may involve membership charges, expedited-transfer fees, ATM fees, interest, or other costs, while some features may be available without a monthly payment. Carefully check the current pricing screen and agreement before accepting an offer, especially when using credit-building or cash-advance products.
Can MoneyLion help me build or monitor my credit?
The app may provide credit scores, credit monitoring, financial insights, and products designed to help eligible users establish or improve credit. However, results are not guaranteed, and different services may report information to different credit bureaus. Using a credit-related product can also involve fees, repayment requirements, or eligibility checks. Read the reporting and repayment terms and continue making all payments on time.
Is MoneyLion safe to use, and what information does it require?
MoneyLion uses account security measures such as encrypted connections, identity verification, and login protections, but no financial app is completely risk-free. Registration may require personal details, identification, income information, and permission to connect external bank accounts. Download the app only from an official store, use a unique password, enable available security features, and review privacy permissions before linking sensitive accounts.











